Where to start in making sense of Medicare and open enrollment.
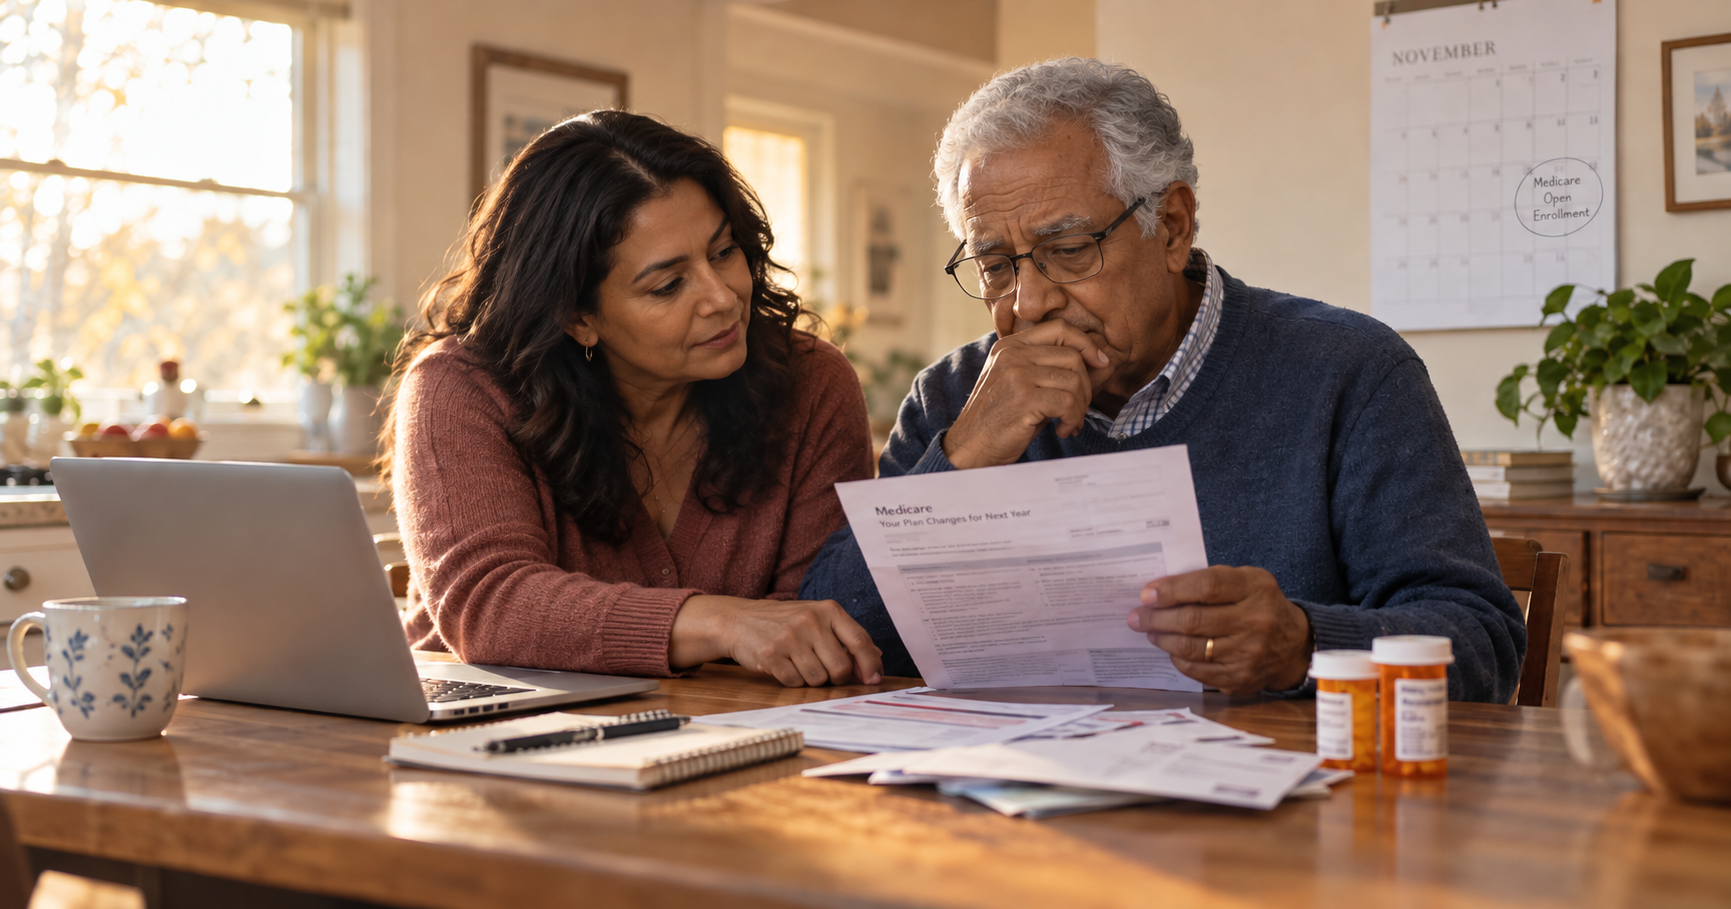
Every fall a pile of mail shows up, and if you’re in the sandwich, some of it is addressed to you and some of it is addressed to your parents but is, let’s be honest, also yours. If you’re helping parents with Medicare open enrollment this year, that window opens October 15 and closes December 7. It lands right on top of workplace benefits season, school forms, and the first round of “so what are we doing for Thanksgiving?” texts.
Nobody puts “compared Dad’s drug plans” on their list of things they did this week. But it’s work. It takes hours and focus, and if it goes wrong, you find out at the pharmacy counter in February. So I want to talk about it like the real job it is.
This one is personal for me right now. Last year my dad had to change Medicare Advantage plans. This fall we found out the new one is being discontinued at the end of the year, so he has to change again. What we were told is that it comes down to insurance companies not making enough money on these plans, plus companies being acquired and merging. Whatever the business reason, the person who absorbs it is my dad. He’s the one who has to make sure every medication and every doctor he relies on is covered somewhere new, for the second year in a row. That creates a lot of anxiety, and honestly, there’s very little good help out there for it.
Quick note before I go further: I’m a caregiver sharing what I’ve learned and where I’ve found good help. I’m not a Medicare counselor, an insurance agent or a tax professional, and nothing here replaces one.
The part nobody likes to say
Helping a parent with Medicare is weirdly intimate. You’re looking at their prescriptions, their doctors and their money. Some parents hand the whole folder over with relief. Others would rather eat the envelope than let their kid see what they pay for a prescription. A lot of us get some version of both, sometimes in the same phone call.
It’s also fine to resent it a little. You can love your mom and still feel your jaw tighten when she says she’ll just keep whatever she had last year, knowing you’re the one who’ll be on hold with the plan if something isn’t covered. That isn’t a character flaw. That’s what carrying the admin for two households feels like.
And if your parent is completely capable of doing this and mostly wants you sitting next to them while they read the fine print, that counts too. Being the second set of eyes is a real kind of help.
What’s actually worth checking this year
During open enrollment, people on Medicare can switch Medicare Advantage plans, change their Part D drug plan, or move between Original Medicare and Medicare Advantage. Whatever they choose starts January 1. If they’re happy and do nothing, they generally stay in the plan they have.
If your parent has a Medicare Advantage plan or a Part D drug plan, they should have gotten an Annual Notice of Change by September 30. It’s easy to toss with the junk mail, and it’s the single most useful thing in the pile. It lays out what’s changing in their current plan next year: the premium, the deductible, the out-of-pocket maximum, which drugs are covered and at what tier, and whether their doctors and pharmacy are still in network. If it never came, the National Council on Aging says to call the plan.
A couple of 2027 changes are worth knowing before you sit down. According to Kiplinger’s roundup of 2027 Medicare changes, the yearly cap on out-of-pocket costs for covered Part D drugs rises to $2,400, up from $2,100 this year, and the maximum Part D deductible goes to $700, up from $615. Kiplinger also reports that a federal program that held down some Part D premiums in 2026 isn’t being extended, so premiums may go up. What that means for families: a plan that worked fine last year isn’t guaranteed to cost the same next year, even if your parent loves it.
Sometimes the change isn’t a price bump. It’s the whole plan going away. My dad is far from the only one this year. In early October, UnitedHealthcare said about 390,000 of its members are in Medicare Advantage plans being discontinued for 2027, and Humana said it expects about 600,000 people to be affected,
according to Cronista. Drug plans are shrinking too: Kiplinger reports the average number of stand-alone Part D plans available has dropped from 30 five years ago to 11 in 2026.
If your parent got a letter saying their plan won’t be offered next year, here’s what
KFF says they need to know. They get a special window from October 15 through the end of February to pick a new plan. If they’re in a Medicare Advantage plan and do nothing, they’ll be moved to Original Medicare by default, and then they’d need to choose a separate Part D plan to keep drug coverage. They may also be able to buy a Medigap policy without medical underwriting, but that right doesn’t last forever. From what we’re living through right now, I wouldn’t lean on the extra months. Picking a new plan by December 7 means it starts January 1, and nobody wants to find out about a gap in drug coverage at the pharmacy.
The most useful hour you can spend is sitting down with the Medicare Plan Finder on Medicare.gov and entering your parent’s actual medications, doses and pharmacy. Plans look alike until you type in the one expensive prescription. It helps to have these in front of you first:
- their Medicare card and their current plan card
- a current list of every medication and dose
- the doctors and the pharmacy they don’t want to give up
- the Annual Notice of Change, if they have one
If nobody in the family has the time or the confidence for this, there’s free help that isn’t trying to sell anything. Every state has a State Health Insurance Assistance Program, or SHIP. Their counselors offer one-on-one Medicare help, the services are free, and they aren’t selling plans. That last part matters this time of year, when the TV ads and phone calls ramp up and everyone seems very eager to “help.” You can find your local SHIP at shiphelp.org. I’d much rather send you to someone trained who doesn’t earn a commission than pretend I know your parent’s situation better than they do.
And if your parent picks a Medicare Advantage plan that turns out to be a bad fit, there’s a second window. From January 1 to March 31, people in Medicare Advantage can switch plans once or go back to Original Medicare. That’s not a reason to skip the homework, but it might lower your blood pressure a little.
The permission slip that saves you hours
If you’ve ever called 1-800-MEDICARE about your parent’s claim and been told they can’t talk to you, this is for you. Your parent can fill out a form called the Authorization to Disclose Personal Health Information (CMS-10106). It lets Medicare talk with you about things like their claims, enrollment and premiums. They can limit it to specific topics, like billing, and they can take it back in writing whenever they want. It’s a lot less loaded than a conversation about power of attorney, which makes it a decent first step for a parent who’s a little touchy about handing over control.
Two caveats. Medicare Advantage plans are run by private insurers, so call the plan to ask how they handle this. And if your parent can no longer give permission at all, that’s a legal question, and an elder law attorney is the right person to ask.
While you’re at it, have the scam conversation now, before the calls start. The FTC says Medicare will never unexpectedly call, email or text to ask for a Medicare number, and it won’t try to sell anything. If someone calls claiming to be from Medicare, hang up and call 1-800-MEDICARE (1-800-633-4227) directly. Caller ID can be faked.
Don’t skip your own enrollment
This is where the sandwich part comes in. A lot of us are doing our parents’ Medicare the same weeks we’re supposed to be picking our own benefits at work, and ours tends to get the leftover attention at 11 p.m.
One change worth knowing: the dependent care FSA limit went up to $7,500 for 2026, from $5,000, under the One Big Beautiful Bill Act. Most of us think of it as a childcare account, and mostly it is. But under IRS rules, a parent can count in narrow cases. They have to be physically or mentally unable to care for themselves, they have to have lived with you for more than half the year, and if the care happens outside your home (adult day care, for example), they need to spend at least eight hours a day in your home. There are dependency and income rules on top of that. That’s a lot of ifs, so treat this as a question for HR and a tax professional, not something to sign up for tonight.
Even if the FSA doesn’t fit your family, it’s worth searching your benefits guide for the word “caregiver.” Some employers offer things like backup care, an employee assistance program or caregiver leave, and they’re often buried on page 40.
If you only do four things
That was a lot, so here’s the short version. If all you can manage this month is a little bit at a time, start here.
- Find the letter. Ask your parent for anything from their plan that came in the mail since September. If it says the plan is changing or ending, that’s your signal to act this year.
- Make the list. Write down every medication with its dose, every doctor, and the pharmacy they use. This one list does most of the work.
- Get help that isn’t selling anything. Call your local SHIP through shiphelp.org, or sit down together with the Medicare Plan Finder and enter that list.
- Decide by December 7. That way the new plan starts January 1 and there are no surprises at the pharmacy.
None of this is glamorous. It’s a weeknight at the kitchen table with a stack of mail and a parent who may or may not want your help. But the hour or two you put in now is time you won’t spend on hold in February, trying to figure out why a prescription suddenly costs so much more than it did in December. It’s your parent walking into the new year knowing their doctors and medications are covered, which for a lot of older adults takes away a kind of worry they don’t always say out loud. And it’s one less thing waiting for you in January, when you’re already back to everyone else’s schedule. You don’t have to become a Medicare expert to do this well. You just have to start with the letter and the list. That’s enough.
Sources
- 2027 Medicare Updates: 8 Changes Retirees Need to Know (Kiplinger, Sept 3, 2026): Part D cap $2,400 and deductible $700 for 2027, premium program not extended, Oct 15 to Dec 7 dates
- Medicare Part D in 2027 (Humana): second confirmation of the $2,400 cap
- What Is a Medicare Annual Notice of Change? (National Council on Aging): ANOC by Sept 30, what to check, call the plan if it didn’t arrive
- How to Read Your Medicare ANOC Letter for 2027 Coverage (WTOP, from U.S. News): Medicare Advantage open enrollment Jan 1 to Mar 31
- What to Know About State Health Insurance Assistance Programs (WebMD): SHIP is free and counselors aren’t selling plans
- SHIP national site: find a local SHIP
- How to Access Your Parents’ Medicare (Kiplinger): form CMS-10106, limits, revoking it, Medicare Advantage plans
- Avoid scams during Medicare’s open enrollment period (FTC): Medicare won’t call unexpectedly, 1-800-633-4227
- New Year, New Dependent Care FSA Limits (Polsinelli, Dec 9, 2025): $7,500 limit for 2026 under the One Big Beautiful Bill Act
- IRS Publication 503: qualifying person rules (can’t care for self, lived with you more than half the year, 8 hours a day in your home for outside care)